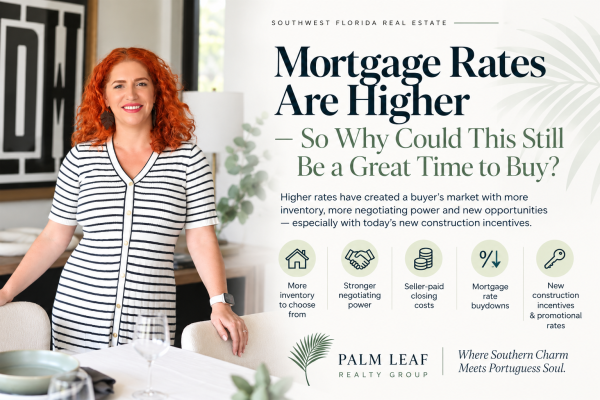
Mortgage Rates Are Higher: Why This Could Still Be a Great Time to Buy
By Palm Leaf Realty Group | Southwest Florida Real Estate
If you've been thinking about buying a home, you've probably asked the same question many buyers are asking me:
“Should I really buy with mortgage rates this high?”
It's a fair question.
As of September 30, Mortgage News Daily's daily average for a 30-year fixed mortgage is approximately 7.54%. Freddie Mac's most recent weekly survey, released September 24, put the average at 7.03%. These are national benchmarks—not a quote for an individual borrower—and your actual rate will depend on factors such as credit, loan type, down payment, points and lender. Mortgage News Daily
So yes, borrowing money costs considerably more than it did when mortgage rates were around 3%.
But that doesn't automatically mean 2021 was a better time to buy than 2026.
The market has changed—and some of those changes are giving today's buyers opportunities they simply didn't have a few years ago.
Remember What Buying A Home Was Like at 3%?
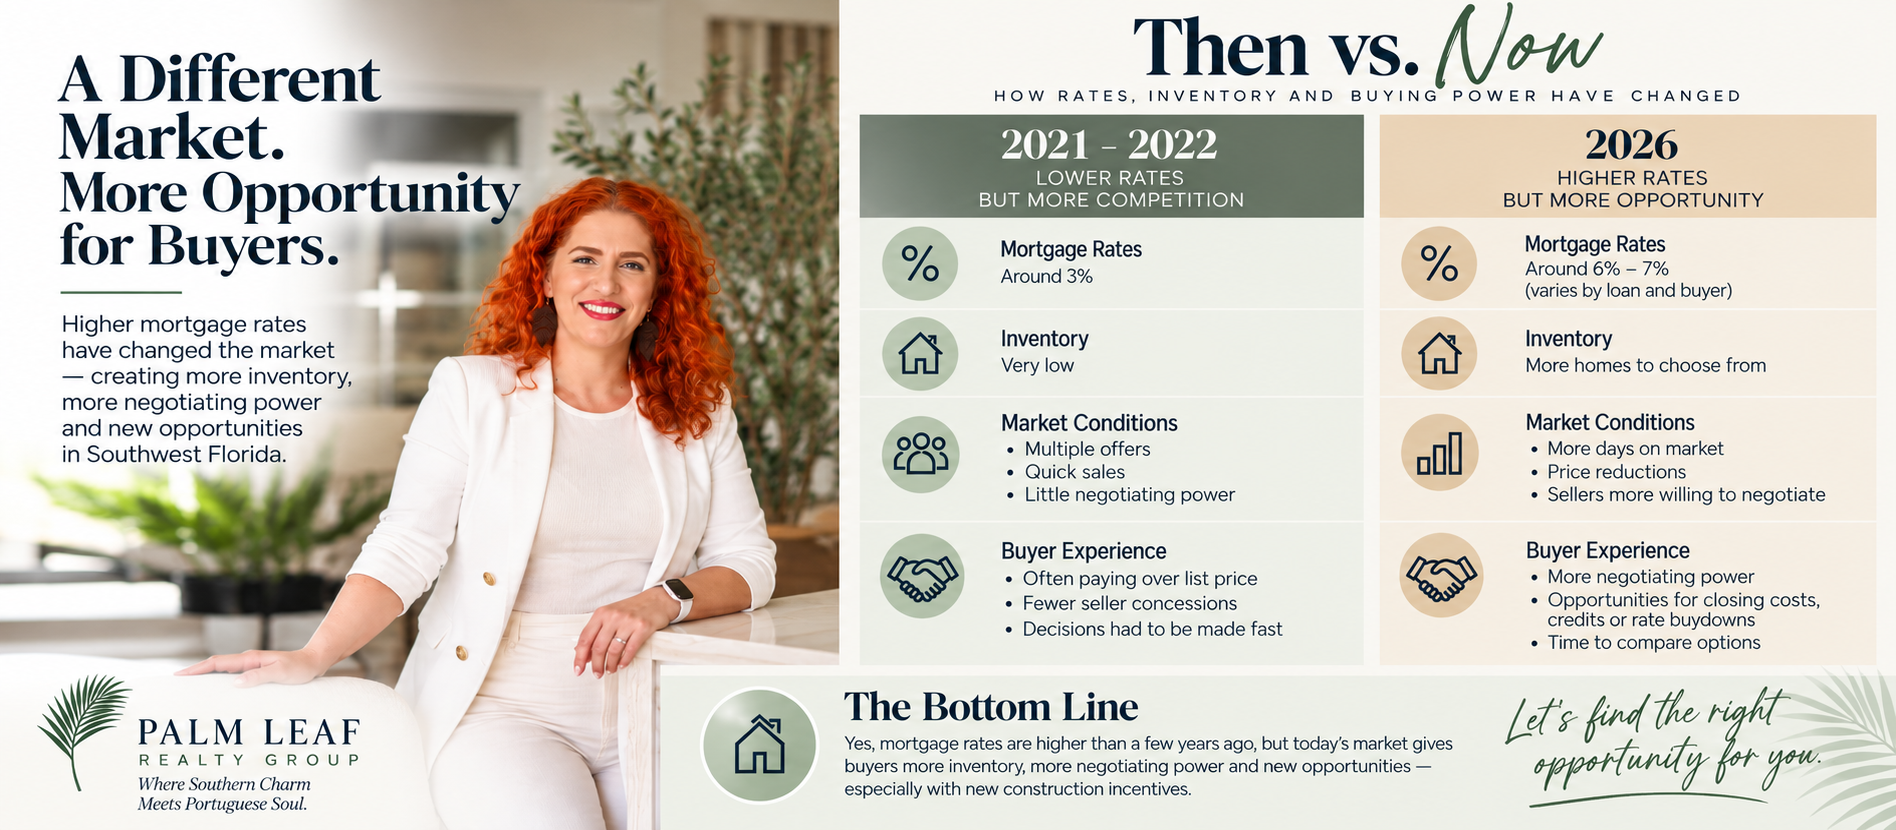
Higher Rates Can Create Different Opportunities
A higher mortgage rate affects your monthly payment and absolutely needs to be part of your budget.
But the interest rate is only one part of the transaction.
Depending on the property and seller, today's environment can give buyers opportunities to negotiate on the purchase price, closing costs, repairs, credits or other terms.
What about Southwest Florida?
This is where working with someone who understands the local market becomes especially important.
Don't Forget New Construction
For many homeowners, staying exactly where they are may make perfect sense.
A 3% mortgage is valuable.
But your mortgage rate shouldn't be the only thing determining where you live for the next 5, 10 or 15 years.
Ask yourself:
Does this house still work for my life?
Maybe you need another bedroom. Maybe you want a pool. Maybe maintaining an older home is becoming expensive. Maybe you want to downsize. Maybe your commute has changed. Maybe you want to be closer to family—or you've decided it's finally time to move to Florida.
If your current home still meets your needs, keeping that low rate may be the right choice.
But if it doesn't, then the conversation becomes bigger than 3% versus 7%.
Your Equity Can Change The Equation
There's another important factor homeowners sometimes overlook: equity.
If you've owned your home for several years, you may have substantial equity available when you sell.
That money could potentially become a larger down payment on your next property, reducing the amount you need to finance.
So instead of comparing your old mortgage rate directly with today's rate, we should look at the entire financial picture:
What will your current home sell for? How much equity will you walk away with? What will you put down? What can we negotiate on the next home? What will the actual monthly payment be?
That's a much more useful comparison.
And What If Rates Eventually Come Down?
Nobody can promise where mortgage rates will go next.
If rates decline in the future, some homeowners may have an opportunity to refinance—but refinancing is never guaranteed and comes with qualification requirements and costs.
That's why I don't recommend buying a home today based on the assumption that you'll definitely refinance later.
The home and payment need to make sense based on today's numbers first.
If rates improve later and refinancing makes financial sense, that's an additional opportunity—not the reason to stretch your budget today.
Don't Wait For A "Perfect" Market
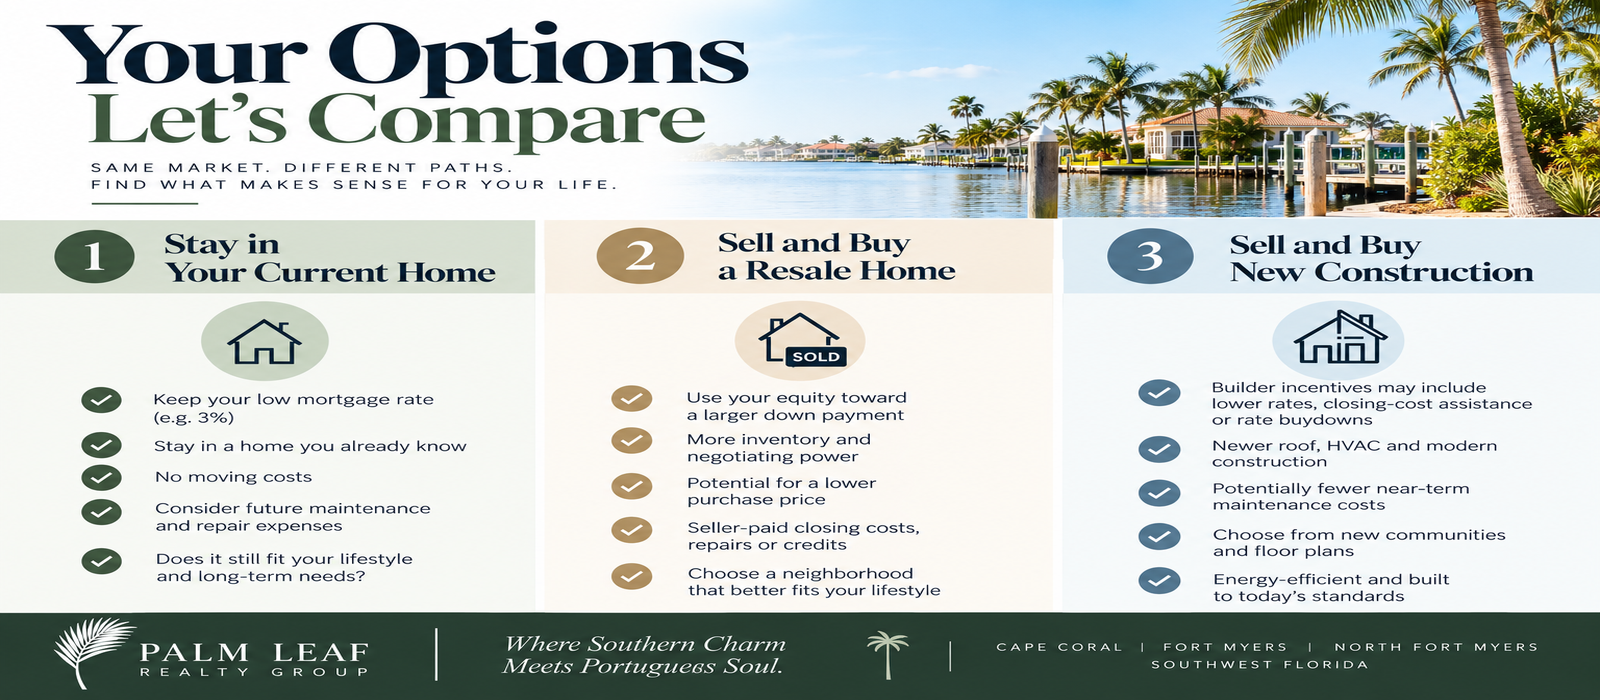
You essentially have three choices: stay in your current home, sell and purchase a resale home, or sell and explore new construction.
None is automatically right or wrong.
My job is to help you put the numbers side by side—including your equity, estimated payment, taxes, insurance, potential seller concessions and builder incentives—so you can see which option actually makes the most sense for your life.
Thinking about buying, selling or making a move in Southwest Florida? Let's look at the numbers before you decide to wait.
Claudia Da Silva, Realtor®
Palm Leaf Realty Group | Coldwell Banker Realty
Cape Coral • Fort Myers • North Fort Myers • Southwest Florida
Where Southern Charm Meets Portuguese Soul.
Mortgage rates and incentives change frequently. Rate figures above are national averages as of September 30, 2026 and are provided for general information; individual rates and loan terms vary.
Why buyers can win now
Resale or new construction?


